Divorce Lawyer Avoid Financial Mistakes: Essential Guide
Introduction
Choose a lawyer who treats divorce as a staged financial process, not a single hearing. In Maryland, financial decisions made during divorce shape long-term net worth and cash flow, so retaining counsel who prioritizes preservation, valuation, and implementable orders matters. This article explains how to select an attorney with financial fluency, which documents to gather and when, how targeted discovery works, how to coordinate experts, and what implementation steps protect retirement and business interests; each section ends with a practical next step to help you move from concern to a documented plan.
Why financial strategy matters in Maryland divorces
Financial strategy aligns legal steps with wealth protection goals. Courts in Maryland resolve support and property division by weighing relevant financial facts, and a lawyer who organizes those facts early can preserve options and leverage during negotiation or litigation. Strategic planning covers preservation of assets, sequencing discovery, identifying tax consequences, and ensuring transfer mechanisms are drafted correctly so orders are actually executable after entry. The right sequence often means protecting complex assets before attempting settlement proposals so that value and implementation options are preserved rather than lost in haste.
How to choose a divorce lawyer focused on finances
Select counsel who asks about assets beyond bank accounts on day one. A financially-focused attorney will probe retirement accounts, equity awards, deferred compensation, business interests, and potential separate-property claims during intake, and will describe how they collaborate with valuation and tax professionals. During your screening call, look for a staged plan that explains discovery priorities, expert use, timing, and how settlement language will translate into post-decree steps rather than vague promises. Bring documents to the first meeting so the attorney can evaluate complexity and outline next steps clearly.
Why local experience and county practice matter
Local familiarity helps tailor strategy to likely procedural expectations. Maryland is composed of multiple counties with differing practical procedures and vendor networks, and counsel who regularly practices in the county where your case will be filed can identify reliable local valuators, plan administrators, and court clerks. This familiarity often speeds discovery, avoids procedural missteps, and positions ask-for-what-you-need negotiations with judges and mediators who are accustomed to local forms of presentation. Ask candidates how frequently they appear in the relevant county and for examples of comparable financial matters they have handled.
Initial documents to gather before your first meeting
Collect current statements and a concise asset inventory before consulting an attorney. Bring recent account statements, retirement summaries, equity award notices, tax filings, business formation documents, and any buy-sell or employment agreements you have access to so counsel can spot immediate risks and preservation needs. Having documentation on hand allows your lawyer to propose tailored temporary protections and to prioritize discovery targets rather than starting from scratch; it also helps the attorney give a realistic outline of likely expert involvement and next steps at the initial intake.
Completing the financial statement accurately
Accuracy and defensibility matter more than presenting a favorable but inconsistent picture. A complete financial statement organizes income, assets, liabilities, and sources of value that may require independent verification, and a lawyer should explain which entries are likely to be scrutinized and why. Your attorney will advise on supporting records to attach, how to describe irregular income streams, and what contingencies to include for later valuation recalculation so the statement serves both settlement and evidentiary purposes without creating exposure through inadvertent omission.
Avoiding common disclosure and reporting mistakes
Omitted items and inconsistent statements invite costly follow-up discovery. Common pitfalls include failing to describe retirement vesting schedules, overlooking equity awards, misstating business distributions, and not disclosing third-party accounts that affect available cash flow. Counsel should describe routine verification tools—such as third-party records or targeted subpoenas—and advise on how to correct or supplement disclosures if new information emerges, preserving credibility while protecting your legal position during settlement talks or contested proceedings.
Targeted discovery and tactical sequencing
Discovery should be sequenced to resolve high-impact questions first. A practical discovery plan prioritizes requests and third-party records that are most likely to confirm or contradict the opposing financial narrative, and it sets benchmarks for when to escalate to subpoenas, depositions, or forensic review. Your lawyer should explain the anticipated outcomes for each discovery task so you can weigh costs against likely benefits and decide when expert analysis is necessary to value or trace disputed assets.
Working with financial experts: roles and coordination
Experts should be engaged with clear scope and measurable deliverables. Attorneys often coordinate with forensic accountants to trace hidden income, Certified Divorce Financial Analysts (CDFAs) to model cash flow and tax outcomes, and valuation specialists to price business interests; the lawyer should explain selection criteria, fee structures, and how each expert’s analysis will be used in negotiation or court. Effective counsel provides a plan for limited-scope engagements that answer specific legal questions without commissioning unnecessary broad reports.
When to use a Certified Divorce Financial Analyst
A CDFA can convert settlement terms into after-tax cash-flow scenarios. Engaging a CDFA is useful when decisions involve trade-offs between different asset classes or tax treatments, and counsel should explain how model outputs inform settlement choices so you can compare alternatives on a net basis rather than only on headline values. Ask the attorney how they integrate CDFA modeling into settlement drafting and whether they use such analyses in mediation or settlement meetings.
When to engage a forensic accountant
Forensic accounting is typically reserved for suspected concealment or complex income streams. Counsel should describe the triggers that prompt forensic review—such as unexplained transfers or inconsistent bank records—and outline the narrow data requests that a forensic accountant will pursue to limit cost. A prudent plan limits forensic engagement to tasks that materially affect valuation or support calculations and explains how forensic findings will be presented to oppose or support settlement positions.
Valuing retirement accounts and transfer mechanics
Retirement division requires both valuation and executable transfer language. Retirement assets may have different tax implications and administrative steps, so your lawyer should explain how orders must be written to allow plan administrators to implement transfers without further litigation. Counsel should also identify potential tax consequences that affect settlement choices and coordinate with experts or plan administrators to confirm feasibility and mechanics before finalizing terms so that transfers occur smoothly after decree entry.
Handling stock options, restricted stock, and deferred compensation
Equity awards and deferred pay need careful timing and valuation input. Options, restricted stock, and deferred compensation can involve vesting, forfeiture risk, and tax timing that materially affect net value; attorneys should describe when valuation, allocation, or offset is appropriate and whether temporary preservation steps such as notifying plan administrators are necessary. Ask how the lawyer treats vesting schedules, what documentation they will request, and how they model likely after-tax outcomes to guide settlement choices.
Business ownership, goodwill, and closely held entities
Business valuation should separate quantifiable enterprise value from personal goodwill claims. For owners of closely held businesses, counsel should advise on valuation methodologies, how to handle management buyouts, and how proposed settlement language will be enforced without disrupting operations. The lawyer should also explain which business documents are essential, how to protect confidential business information during the process, and how to craft buyout timing and payment terms that align with business continuity and tax considerations.
Tax considerations to address without offering tax advice
Tax effects often determine which settlement option protects long-term net worth. A family law attorney should flag likely tax implications of proposed division terms and recommend when to involve a tax professional to model scenarios; however, tax specifics require coordinated tax advice. Counsel should still translate settlement alternatives into likely after-tax outcomes in broad terms so you can compare options and decide whether to accept cash now, defer, or exchange asset classes for more favorable tax treatment.
Temporary orders and asset preservation while cases proceed
Temporary protections keep options intact while negotiations or discovery proceed. Many contested matters benefit from interim orders that preserve assets, limit transfers, and address temporary support so neither party prejudices the other during valuation and discovery. Your lawyer should explain which temporary measures may be appropriate early on, how to request them, and what evidence is needed to support those requests so you avoid losing leverage while longer term arrangements are negotiated.
Drafting settlement language that implements the deal
Settlement terms must translate into enforceable, implementable steps. A settlement that reads well in principle can fail at the implementation stage unless it specifies transfer mechanics, tax allocation, timing, and remedies for nonperformance; good counsel drafts detailed implementation language and includes contingencies for valuation adjustments or future disputes. Ask for an implementation checklist that names responsible parties, deadlines, and the documents or administrative steps required to complete the agreed transfers.
Managing expert fees and keeping costs proportional
Cost management is a deliberate part of financial strategy, not an afterthought. Attorneys should explain staged expert engagement, limited-scope analysis, and other cost-containment approaches so expert work is targeted to the questions that matter most. Expect counsel to discuss trade-offs between engaging an expert to fully test a claim versus using focused discovery to narrow disputed items; a thoughtful budget-conscious plan ties anticipated expenses to likely benefits and decision thresholds.
Cross-jurisdiction assets and multi-state complications
Assets and income across jurisdictions typically require coordinated discovery and implementation. When assets, employers, or plan administrators are located outside Maryland, counsel should explain how to obtain records, how to coordinate with out-of-state experts or counsel when necessary, and how enforcement or transfer mechanics may be affected by differing administrative practices. Early disclosure of multi-state ties allows counsel to set a sequence for discovery, valuation, and implementation that minimizes surprise and preserves enforceable terms.
Post-decree implementation, enforcement, and common pitfalls
Many disputes occur after the decree when transfers are not properly implemented. A finance-focused attorney builds post-decree checklists into settlement documents, identifies who will notify plan administrators or trustees, and includes dispute-resolution language to limit re-litigation. Common implementation pitfalls include ambiguous transfer language, missing deadlines, and failure to secure tax allocations; your lawyer should explain how to avoid these by documenting responsibilities and preserving remedies if counterparties fail to perform.
Preparing for your first consultation: a focused intake checklist
Arrive prepared so the attorney can present a realistic, staged plan. Provide a concise asset inventory, recent account statements, summaries of equity awards and business interests, and a list of the questions you want answered about valuation, tax exposure, and transfer mechanics; this allows counsel to propose immediate preservation steps and a prioritized discovery plan. Use the consultation to evaluate whether the lawyer presents a documented process with stage-gates and expected outcomes rather than generic assurances.
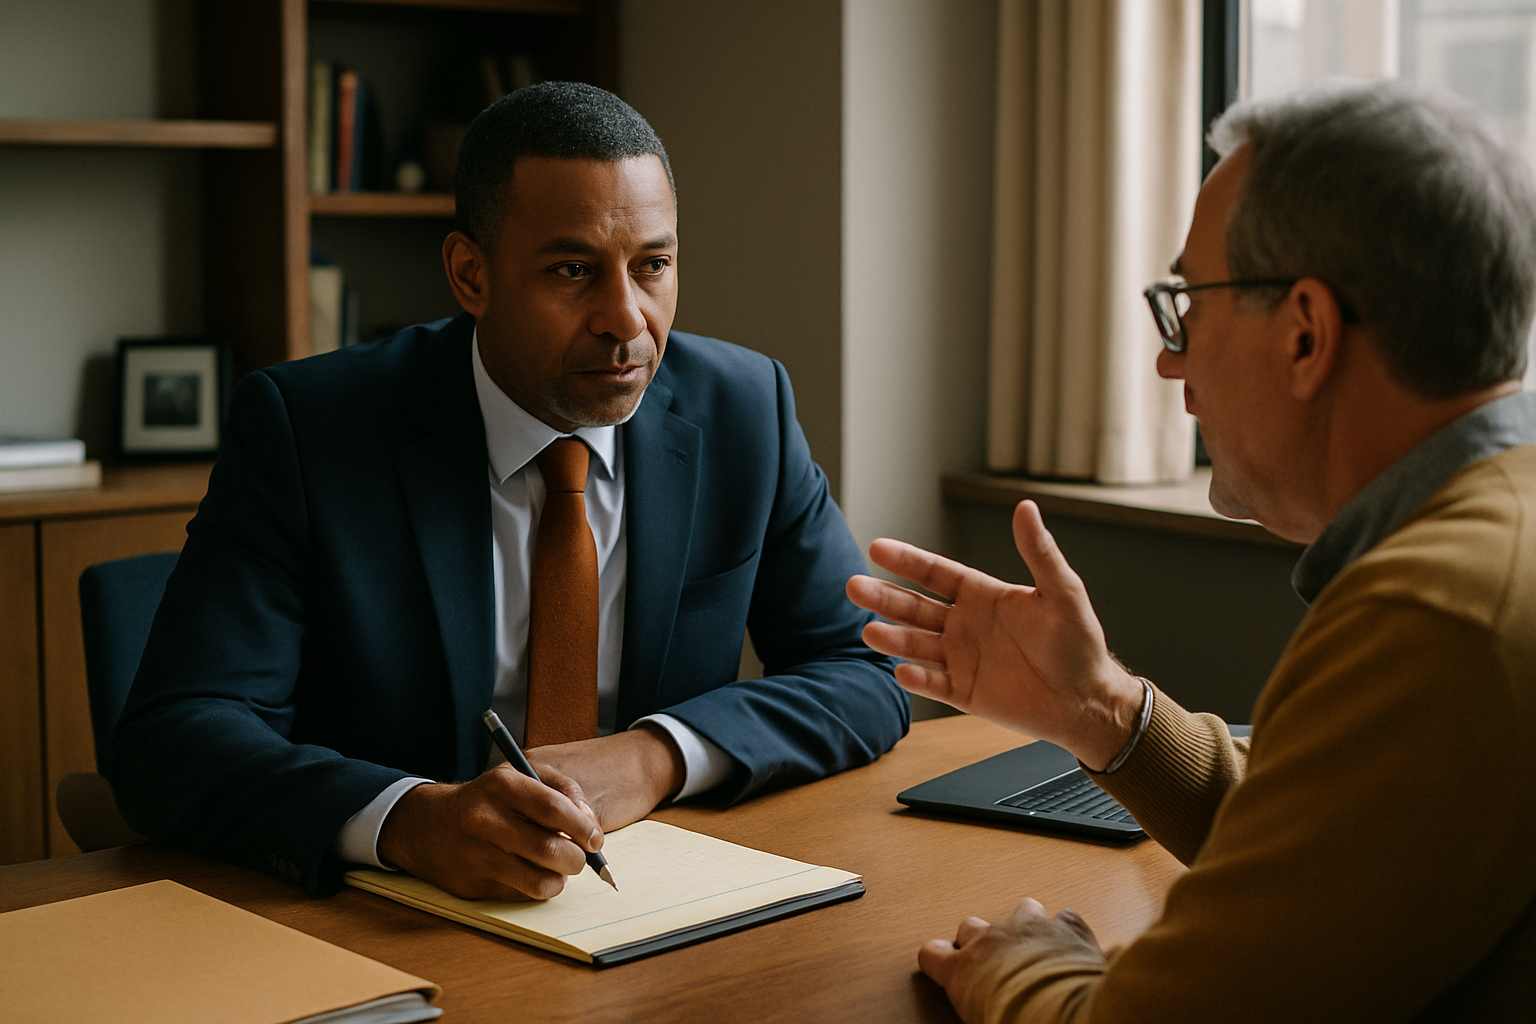
divorce lawyer avoid financial mistakes: planning, not promises
divorce lawyer avoid financial mistakes by treating divorce as a sequence of financial decisions you can plan for. The right approach starts with early, focused preservation steps, a prioritized discovery schedule, targeted expert engagement, and settlement language that implements the economic deal rather than relying on informal assurances; counsel should present a staged strategy with decision points tied to documented outcomes and cost estimates. Personalized guidance means translating asset swaps into likely after-tax cash flow, identifying where temporary orders are prudent, and building an implementation checklist to limit post-decree disputes. If you want to move from general concern to a concrete plan, schedule a consultation with Divorce With a Plan through divorcewithaplan.com so we can tailor a strategy for your specific financial profile and goals.
Frequently Asked Questions
These are the questions Maryland families ask most often about this topic. Each answer is general information rather than advice about a specific case, and the right approach always depends on the details of your situation.
Can I finalize a divorce before resolving the financial settlement?
Filing for divorce starts the legal case, but financial settlement and implementation often continue afterward; courts typically allow negotiation or litigation of financial issues while the case is pending. Discuss with counsel whether temporary protections or preservation orders are advisable so rights and assets are not compromised while settlement terms are finalized.
What documents should I bring to my first meeting with a divorce lawyer?
Bring a concise inventory of assets and copies of recent account and retirement statements, equity award notices, business formation documents, and relevant agreements so counsel can identify immediate risks and preservation needs. This enables the attorney to propose prioritized next steps and to estimate likely expert involvement.
When should a forensic accountant be used in a divorce?
A forensic accountant is typically considered when there are signs of hidden income, complex business transactions, or unexplained transfers that could affect valuation or support calculations; counsel should describe specific triggers and the focused tasks a forensic review would perform so cost and benefit can be weighed.
How are retirement accounts handled to avoid implementation problems?
Retirement transfers require both valuation and precise transfer language so plan administrators can implement orders; attorneys usually coordinate with experts and plan administrators to confirm mechanics and draft enforceable terms that specify timing, responsible parties, and tax considerations to reduce post-decree disputes.
This article is for general informational purposes only and does not constitute legal advice. Maryland law changes, and every situation is unique. Consult a qualified Maryland family law attorney about your specific circumstances.